Investing the right way — the four core rules
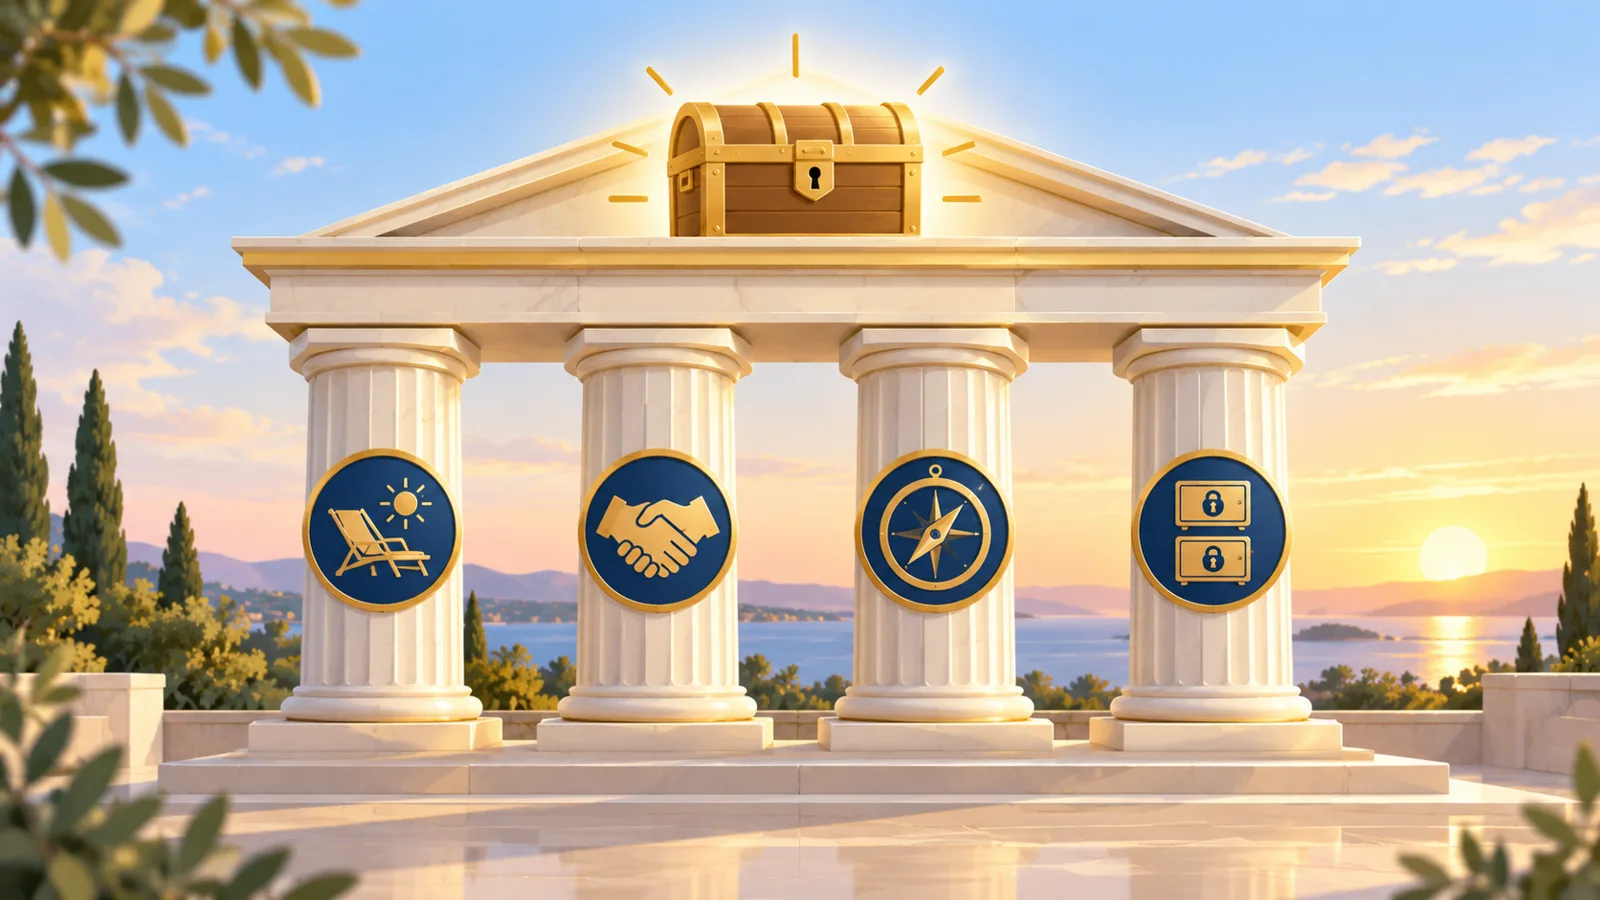
SMSFs can invest in a wide range of assets — shares, ETFs, property, cash, term deposits and more. But every investment has to pass four simple rules. If you remember these, you’ll stay out of most trouble.
| Rule | Where it comes from | In one line |
|---|---|---|
| Sole purpose test | Section 62, SIS Act | The fund exists only to pay retirement (and death) benefits |
| Arm’s length | Section 109, SIS Act | Deal on normal commercial terms — like strangers would |
| Investment strategy | Regulation 4.09, SIS Regulations | Have a written plan, follow it and review it |
| Keep assets separate | Regulation 4.09A, SIS Regulations | Fund money and assets never mix with yours |
3.1 The sole purpose test (s62)
Your SMSF must be run for one purpose: providing retirement benefits to members (or to their dependants if a member dies). Nobody should get a benefit from the fund today.
3.2 Arm’s length dealings (s109)
If the fund deals with anyone — especially family or a related business — the price and terms must be the same as between two unrelated parties. Market rent, market price, commercial interest rates.
Income from a deal that isn’t at arm’s length can be taxed as non-arm’s length income (NALI) at 45% instead of the normal 15%.
3.3 Have an investment strategy (Reg 4.09)
Every SMSF must have a written investment strategy that the trustees follow and review regularly (at least once a year is good practice). It should consider:
- Risk and return — what the fund is aiming for and how much risk is acceptable.
- Diversification — or why you’ve chosen not to spread investments (e.g. one large property).
- Liquidity — enough cash to pay tax, fees and expenses.
- Paying benefits — can the fund pay pensions or lump sums when members need them?
- Insurance — whether the fund should hold life or disability cover for members.
3.4 Keep fund assets separate (Reg 4.09A)
- The fund has its own bank account — never pay fund expenses from your personal account, or personal bills from the fund.
- Investments are held in the fund’s name (or the trustee “as trustee for” the fund).
- Don’t store fund assets (such as artwork or bullion) in your home for personal use.
3.5 Property in your SMSF
Property is one of the most popular SMSF investments — and the area where the four rules above are tested most often.
| Residential property | Commercial property (business real property) | |
|---|---|---|
| Can the fund buy it? | Yes — from an unrelated seller, at market value | Yes — and it can be bought from a member or related party at market value |
| Can members or relatives live in it, rent it or holiday in it? | ✘ No — not even for a weekend | A related business can lease it, at market rent with a written lease |
| Can the fund borrow (an SMSF loan via a bank or lender, formally an LRBA) to buy it? | ✘ No — no new residential SMSF loans from 10 Aug 2026 | ✔ Yes — if used wholly and exclusively in a business |
| Valuation | Market value each year — at My SMSF, a formal valuation every 3 years with an accepted automated valuation in between | A formal valuation every year |
- Title is held by the trustee as trustee for the fund — or by a separate holding (bare) trust if there is a loan.
- Rent goes into the fund’s bank account and every property expense is paid from it — never from your personal account.
- Repairs vs improvements: fund money can repair or improve a property, but borrowed (SMSF loan) money can only be used for repairs and maintenance — not to change the asset into something different (e.g. knock down and rebuild).
- Holiday homes and cabins: see the cabin distinction below.
The cabin distinction — holiday home vs accommodation business
Since 10 August 2026 a new SMSF loan can only be used for business real property — land and buildings used wholly and exclusively in a business. So the question for a cabin isn’t “is it residential?” but “is it used wholly and exclusively in a genuine business?”
| Holiday home / holiday cabin | Cabin in an accommodation business | |
|---|---|---|
| Example | A beach house or bush cabin the fund rents out through an agent or Airbnb | Cabins in a holiday park, caravan park or farm-stay that operates as a business (bookings, reception, cleaning, marketing) |
| How it’s treated | Residential property | May be business real property — part of the business’s premises |
| New SMSF loan after 10 Aug 2026? | ✘ No | ✔ Yes — if it is business real property |
| Buy with fund money (no loan)? | ✔ Yes | ✔ Yes |
| Personal use by members or relatives? | ✘ No | ✘ No — unless leased to a related business at market rent with a written lease |
What about a related-party loan?
A loan to the fund from a member, a relative or their company is still an SMSF loan — so the same rule applies, whoever the lender is.
| Property | Related-party SMSF loan after 10 Aug 2026? |
|---|---|
| Residential — including a stand-alone holiday home or cabin | ✘ No |
| Business real property — commercial premises, or cabins in a genuine accommodation business | ✔ Yes — on the ATO’s safe-harbour terms (PCG 2016/5) |
| Existing residential SMSF loan entered before 10 Aug 2026 | ✔ Yes — continues and can be refinanced on commercial terms |
Buying residential? The member can borrow personally and contribute the money (within the caps), or buy alongside the fund as tenants in common with the member’s share financed personally — the fund’s own share can’t be borrowed.
3.6 Common property expense claims
| Expense | How it’s treated in the fund |
|---|---|
| Interest on an SMSF loan | Deductible |
| Council rates, water rates, land tax | Deductible |
| Strata / body corporate levies | Deductible |
| Building and landlord insurance (in the fund’s name) | Deductible |
| Property management fees and advertising for tenants | Deductible |
| Repairs and maintenance | Deductible |
| Depreciation on the building and fittings (with a quantity surveyor’s schedule) | Deductible over time |
| Stamp duty, legal fees and costs of buying | Not deductible — added to the property’s cost base for capital gains tax |
| Improvements and renovations | Not deductible upfront — capital works, depreciated or added to the cost base |
| Loan principal repayments | Not deductible |
| Travel to inspect the property | Generally not deductible for residential rental property |
| Any cost paid personally by a member | Not claimable by the fund — and treated as a contribution |
3.7 GST — what can the fund claim?
| Situation | GST position |
|---|---|
| Residential rent | Input-taxed — no GST is charged on rent and no GST credits can be claimed on residential expenses. |
| Commercial rent | Taxable — if the fund is registered for GST it charges GST on the rent and claims GST credits on property expenses (rates and land tax have no GST in them). |
| When to register | Compulsory once taxable income (e.g. commercial rent) reaches $75,000 a year; optional below that. A registered fund lodges a BAS — monthly or quarterly. |
| Buying a tenanted commercial property | Often GST-free as a going concern if both buyer and seller are registered and the lease continues. |
| Buying new residential property | The fund (as buyer) may need to withhold GST at settlement and pay it to the ATO. |
| Fund running costs | A GST-registered fund can generally claim a reduced input tax credit of 75% for certain investment and administration services. Tax, audit and legal (setup) fees don’t qualify. |
3.8 Quick check — is this allowed?
| Situation | Allowed? | Why |
|---|---|---|
| Buy ASX shares or ETFs in line with the investment strategy | ✔ Yes | Normal investment for retirement |
| The family stays at a holiday house the SMSF owns, even for a weekend | ✘ No | Present-day benefit — fails s62 |
| Lease a commercial office the SMSF owns to your own business at market rent | ✔ Yes | Business real property, on arm’s length terms |
| Rent the same office to your business at half the market rent | ✘ No | Not arm’s length — s109 breach and NALI risk |
| Hang SMSF-owned artwork in your lounge room | ✘ No | Personal use of a fund asset |
| Buy a holiday cabin with fund money and rent it to unrelated holidaymakers at market rates | ✔ Yes | Allowed with fund money — no personal use by members or relatives |
| Take a new SMSF loan in 2027 to buy a stand-alone holiday cabin | ✘ No | Residential — new SMSF loans are limited to business real property |
| Take a new SMSF loan to buy cabins that form part of a genuine holiday-park business | ✔ Yes | Can be business real property — get written advice first |
| A member lends the fund money to buy a residential unit in 2027 | ✘ No | A related-party loan is still an SMSF loan — residential is banned |
| Rent the SMSF’s residential unit to your adult son | ✘ No | Residential property can’t be leased to a related party |
| Pay your personal credit card from the SMSF bank account | ✘ No | Mixing assets — Reg 4.09A breach |
Key takeaways
- s62 — retirement benefits only, no benefits today.
- s109 — commercial terms with everyone, especially related parties.
- Reg 4.09 — written investment strategy, followed and reviewed.
- Reg 4.09A — fund money and assets kept completely separate.
- Property — no personal use; residential only from unrelated sellers; claim running costs, not purchase costs; residential = no GST.
This free course covers the essentials. The full SMSF Trustee Education Course ($11) goes deeper across 10 lessons — setup steps, trustee structures, contribution caps, pensions and winding up a fund.
General information only — not personal financial, tax or legal advice. Rules referenced are current as at October 2026. Check the ATO website or speak to a licensed adviser before acting.