SMSF commercial property: the one property your fund can still borrow for
Since 10 August 2026, business real property is the only real estate a new SMSF loan can buy. Buy offices, shops, warehouses, or your own business premises and lease them back at market rent.
Business real property, in plain terms
The property must be used wholly and exclusively in one or more businesses. Use matters more than zoning: a commercially zoned building with a flat upstairs may not qualify.
Offices
Strata or freehold offices and medical or professional suites.
Retail
Shops, showrooms and café premises leased to trading businesses.
Industrial
Warehouses, factory units, workshops and storage.
Primary production
Working farmland. A home on up to 2 hectares can be included.
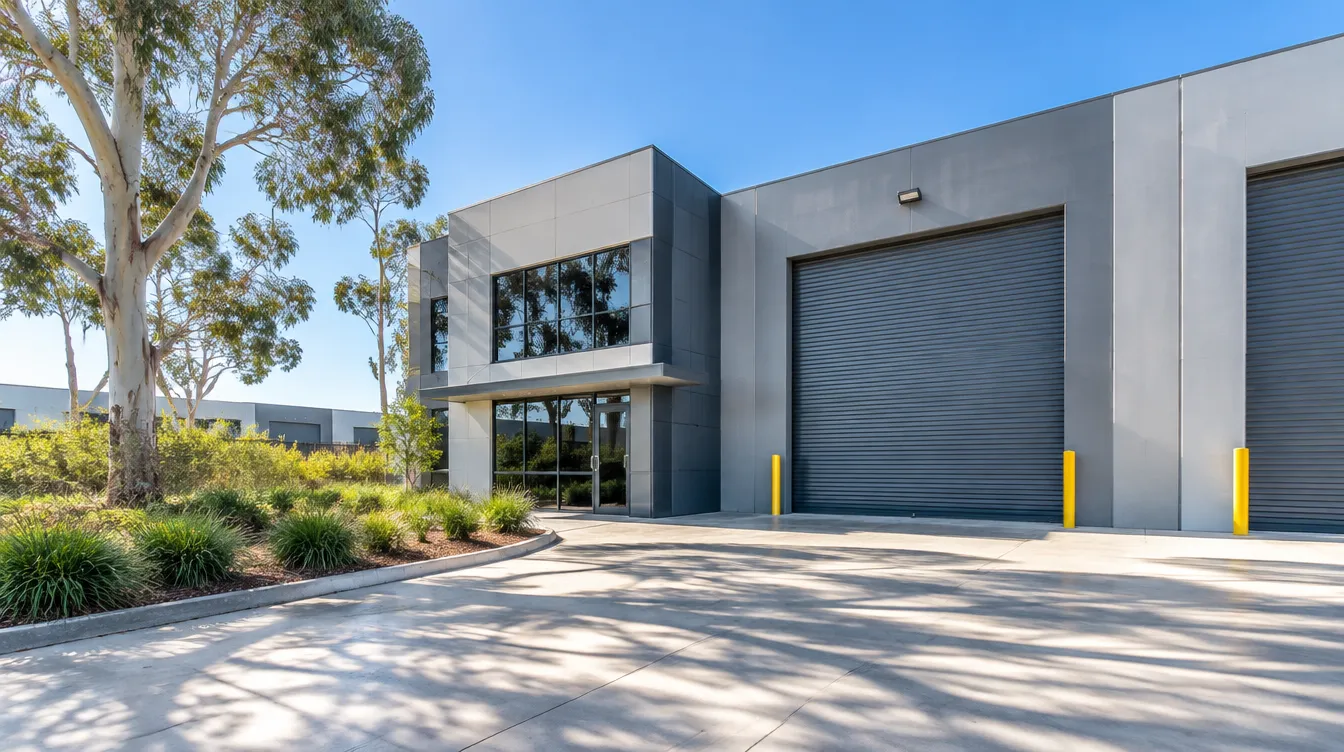
Warehouses, offices and shops your fund can own
Buy premises used wholly and exclusively in a business, including your own and lease them at market rent.
How an SMSF commercial loan is set up
The lender can only claim the property if the loan defaults. Other fund assets are protected.
NSW example: $650,000 commercial property, 70% LVR. Costs are stamp duty $23,437, SMSF setup $990, bare trust $1,770 and legal and loan costs of about $2,250.
Buying commercial property with your SMSF
Check the deed and investment strategy
Both need to allow borrowing and direct property.
Confirm the property qualifies
We check it is business real property before you commit, including any mixed-use or vacant-land issues.
Set up the bare trust and get pre-approval
The holding trust must exist before the contract is signed in its name. We can refer you to a lender or broker and may receive a referral fee.
Due diligence and exchange
Review the lease, tenant, zoning, GST treatment and valuation.
Settle and document the lease
If your business is the tenant, sign a written lease at market rent, backed by an independent valuation.
Keep arm’s-length records every year
Rent received on time, loan repayments from the SMSF account, annual valuation, accounts and audit.
Stamp duty on a $650,000 commercial property
Two jurisdictions charge no duty on most commercial purchases. Rates as at September 2026.
General rates as at September 2026. VIC: duty is paid once, then the property moves to the commercial and industrial property tax. Commercial purchases may also attract GST.
| State | Duty | Note |
|---|---|---|
| SA | $0 | No duty on non-residential land (not primary production) |
| ACT | $0 | Duty-free up to $2.1m, based on Crown lease use |
| QLD | $22,275 | General rate |
| NSW | $23,437 | General rate |
| TAS | $24,623 | General rate |
| WA | $24,890 | General rate |
| NT | $32,175 | 4.95% of value |
| VIC | $34,070 | Paid once, then 1% of site value a year after 10 years |
Commercial purchases may also attract GST. See residential and commercial duty rates by state and check your state revenue office before you exchange.
Where commercial property can go wrong
Vacancy
Commercial vacancies can run for months and the fund still has to make loan repayments.
Concentration
One large asset can make up most of the fund. The investment strategy needs to address this.
Related-party leases
Rent below market, or unpaid rent, can create non-arm’s-length income taxed at 45%.
SMSF commercial property questions
Can my SMSF buy my existing business premises?
Yes. Business real property is an exception to the related-party acquisition rule. The fund pays market value and your business leases it back at market rent.
Can I transfer the property into my SMSF instead of selling it?
Yes, as an in-specie contribution, within contribution caps, or as a part-sale. Stamp duty and CGT may apply, so get advice.
What balance do lenders want?
It varies by lender. Most want a deposit of 30–40% plus costs and some cash left in the fund after settlement.
Can my SMSF still borrow to buy residential property?
Not with a new loan. From 10 August 2026, a new LRBA can only buy business real property. See what changed and what’s protected.
Thinking of buying your premises through super?
Free call to check the property, the lease and the numbers.
1300 545 516General information only, current as at 24 September 2026. It does not consider your personal circumstances and is not financial advice.