Compliance and your annual obligations
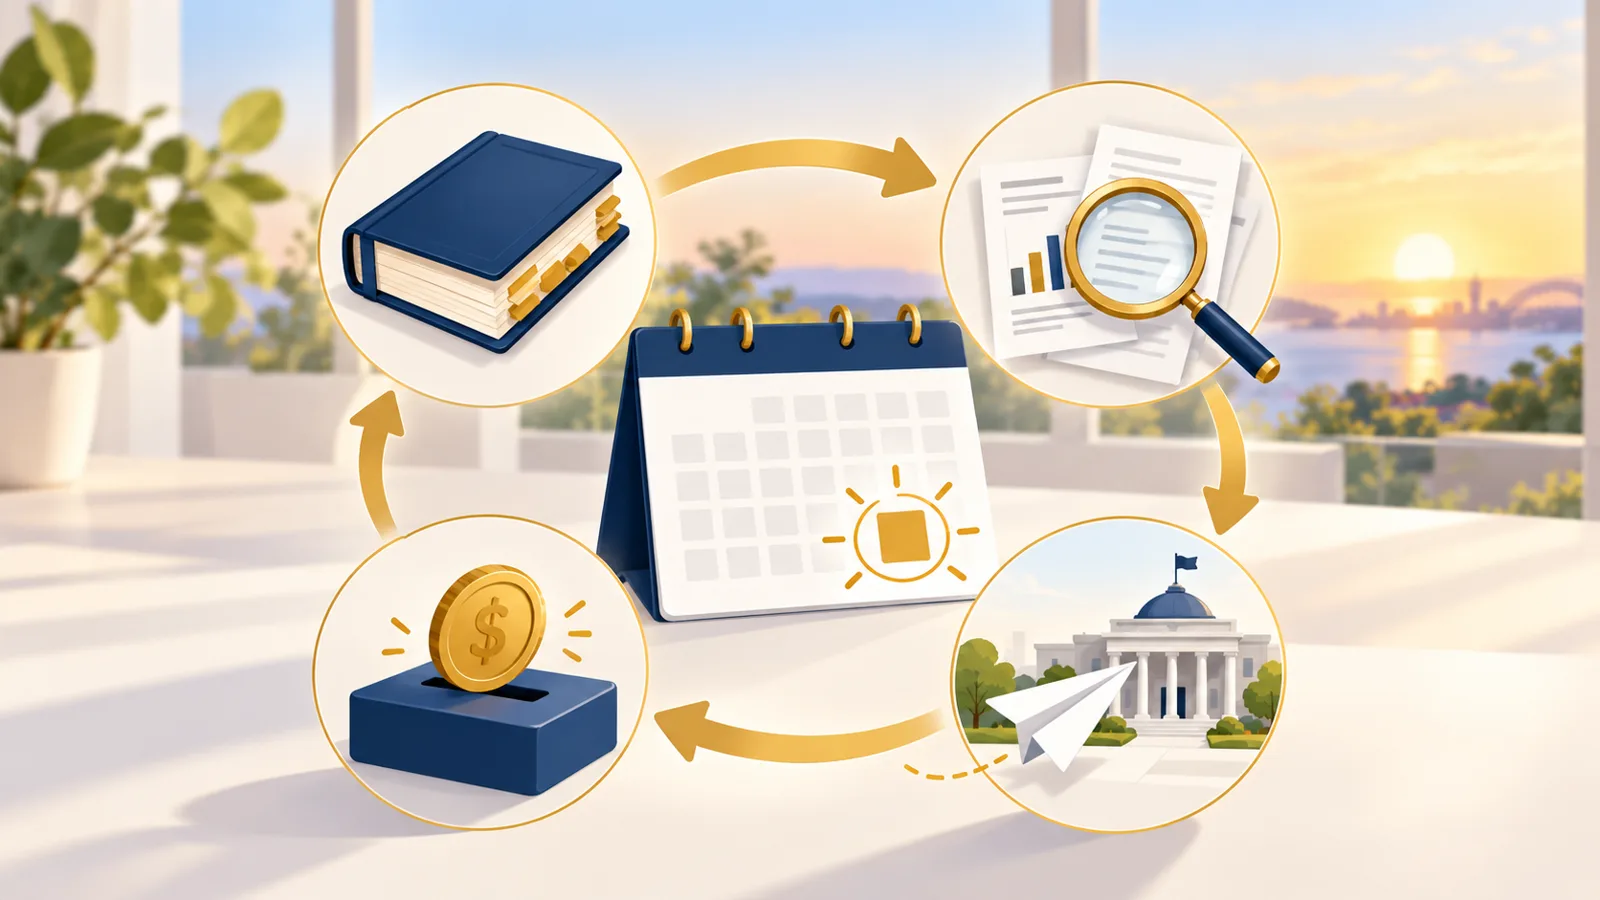
Every year your SMSF goes through the same cycle: prepare accounts, get an independent audit, lodge a return and pay the ATO levy. Along the way there are three rules that trip up trustees most often — lending to members, in-house assets and borrowing.
4.1 The annual cycle
| Step | What happens |
|---|---|
| 1. Financial statements | Accounts and member statements are prepared for the year ending 30 June. |
| 2. Independent audit | An ATO-approved SMSF auditor checks the accounts and that the fund followed the rules. Trustees must appoint an auditor each year and provide documents within 14 days of a request. |
| 3. Lodge the SMSF annual return | Reports income tax, regulatory information and member contributions to the ATO. The audit must be finished before the return is lodged. |
| 4. Pay the supervisory levy | An annual ATO levy (currently $259) is paid with the return. |
4.2 No loans or financial help to members (s65)
An SMSF must not lend money or give financial help to a member or their relatives. That includes:
- Lending fund money to a member — even “just until payday”.
- Using fund assets as security for a member’s personal loan.
- Paying a member’s personal expenses and “sorting it out later”.
This is one of the most common breaches auditors report — and one of the easiest to avoid.
4.3 In-house assets — the 5% limit
An in-house asset is a loan to, investment in, or lease of a fund asset to a related party (a member, relative, or a business they control). The rule is simple:
Exception: business real property (e.g. a commercial office or factory) leased to a related business at market rent is not an in-house asset.
4.4 Borrowing restrictions
As a general rule, an SMSF can’t borrow money. There are only narrow exceptions:
- Short-term borrowing (up to 90 days, max 10% of assets) to pay benefits or cover settlement of a share trade.
- SMSF loans (via a bank or lender) — formally called limited recourse borrowing arrangements (LRBAs) — a loan to buy a single asset held in a separate holding trust, where the lender can only claim that asset if things go wrong.
Cabins — the distinction: a holiday home or holiday cabin rented out on its own is residential — no new SMSF loan (the fund can still buy it with its own money). A cabin that is part of a genuine accommodation business (e.g. a holiday park or farm-stay run as a business) may be business real property, so a new SMSF loan can be used. Get written advice before borrowing.
4.5 Quick check — compliant or not?
| Situation | Compliant? |
|---|---|
| The fund lends $20,000 to a member’s son for a car | ✘ No — s65 |
| The fund owns shares in a related family company worth 4% of total assets | ✔ Yes — under the 5% limit |
| The fund takes out a new SMSF loan in 2027 to buy a residential unit | ✘ No — new residential SMSF loans banned from 10 Aug 2026 |
| The fund takes out an SMSF loan to buy a warehouse leased to an unrelated tenant | ✔ Yes — business real property |
| Trustees give the auditor the bank statements within 14 days of the request | ✔ Yes |
Key takeaways
- Each year: accounts → independent audit → lodge annual return → pay the levy.
- s65 — never lend to, or financially help, members or relatives.
- In-house assets — keep under 5%; fix it within a year if you go over.
- Borrowing — generally banned; new SMSF loans now limited to business real property.
This free course covers the essentials. The full SMSF Trustee Education Course ($11) goes deeper across 10 lessons — setup steps, trustee structures, contribution caps, pensions and winding up a fund.
General information only — not personal financial, tax or legal advice. Rules referenced are current as at October 2026. Check the ATO website or speak to a licensed adviser before acting.