
Inflation, high interest rates and falling values are testing every property investor. Here is why SMSF property, with three cash-flow streams and concessional tax, may be holding up better than property held outside super.
Inflation is up, interest rates are up and property values are down. If you own an investment property right now, you are feeling it. But here is the question I keep coming back to: is SMSF property holding up better against inflation and high interest rates than property owned personally? With the 2026 Federal Budget changing the rules for investors outside super, I think the answer is increasingly yes, for the right fund.
Updated: 14 November 2026 | Reading time: approximately 10 minutes
The Reserve Bank lifted the cash rate to 4.85% in November 2026 and Cotality reported national dwelling values had fallen 6.7% from their March peak to October 2026.
For property investors, including SMSF property owners with loans, rising interest rates are only part of it. The pressure is coming from every direction: higher repayments, rising insurance and maintenance costs, softer values and changes to how residential investment property is taxed.
But not every investor is feeling it the same way. There is a real difference between a property you hold in your own name and one held inside your self-managed super fund.
The short version is this: an SMSF can draw on three separate streams of cash flow to carry its property and the income it earns is generally taxed at a much lower rate. For trustees who are 15 to 25 years from retirement, those two structural advantages are worth a closer look.
Contents
- The three cash-flow streams behind SMSF property
- What about property investors outside super?
- Why SMSF property tax deserves another look
- The 15–25 year horizon: time is on your side
- The catch: new SMSF residential loans are restricted
- Could falling prices be an SMSF opportunity?
- What existing SMSF property trustees should do now
- Is SMSF property more attractive after the Budget?
- Frequently asked questions
1. The Three Cash-Flow Streams Behind SMSF Property
One of the most under-appreciated things about SMSF property is that the rent does not have to carry the whole load. A fund can have three separate sources of money coming in.
Stream one: ongoing super contributions
Employer contributions, salary sacrifice and eligible personal contributions all flow into the fund on a regular basis.
For 2026–27, the general concessional contributions cap is $32,500 per member, subject to the eligibility rules and any carry-forward amounts you have available. Concessional contributions are generally taxed at 15% when they hit a complying SMSF and the rest is available for the fund’s permitted purposes.
Picture a couple who both work and both contribute to the same SMSF. Their combined contributions can add real annual liquidity alongside what the fund’s investments earn. That money can help service an existing property loan, cover expenses or be invested elsewhere.
When interest rates rise, those contributions are often what keeps an SMSF property loan comfortable without touching the rent.
Just remember that contributions are additions to retirement capital, not investment earnings. They are capped, they come with eligibility rules and they will slow down or stop when you retire.
Stream two: rental income, taxed at 15%
This is where the gap between SMSF and personal ownership really opens up.
Net rental income in a complying SMSF is generally taxed at 15% in accumulation phase. Hold the same property personally and the net rental profit is taxed at your marginal rate. If you are on 37%, that difference adds up quickly.
Take $20,000 of annual net taxable rental profit:
| SMSF accumulation phase | Personal ownership | |
|---|---|---|
| Net taxable rental profit | $20,000 | $20,000 |
| Assumed tax rate | 15% | 37% |
| Tax payable | $3,000 | $7,400 |
| Profit after tax | $17,000 | $12,600 |
Illustrative only. The personal example assumes the full profit falls in the 37% bracket and excludes the Medicare levy and other tax adjustments. SMSF outcomes differ for retirement-phase assets, non-arm’s-length income and members subject to additional super earnings tax.
That is $4,400 a year more kept inside the fund on exactly the same rental profit, which goes a long way towards absorbing higher interest rates on an SMSF property loan. Over 15 or 20 years, keeping more after-tax income inside the fund builds liquidity and investment capacity.
Of course, rent is not profit. Interest, rates, insurance, repairs and other deductible costs all come off before you get to the taxable amount.
Stream three: interest, dividends and other investments
Your SMSF does not have to be a one-property fund. It can also hold cash, term deposits, Australian and international shares, ETFs and other permitted investments and each of those can throw off income.
A fund holding property alongside a diversified share portfolio might be receiving quarterly dividends, interest and franking credits. That income can cover admin costs, top up cash reserves or support permitted loan repayments.
The key point: your fund’s total liquidity and servicing position can be a lot stronger than the property’s rental yield on its own suggests.
The caveat is that distributions are not guaranteed and other assets may need to be sold to raise cash. A well-run SMSF should never depend on contributions or dividends always arriving on time and in full. Our guide to SMSF liquidity strategy covers how to plan for that.
2. What About Property Investors Outside Super?
Higher interest rates hit SMSF property and personally held property alike, but the way each absorbs the hit is very different.
For investors holding property in their own name, the picture looks different.
They can also use their wages, savings and other investments to support a rental property. The difference is that the property sits inside their personal finances, competing with the mortgage on the family home, school fees and the grocery bill, rather than in a separate, regulated retirement fund.
Think about an investor carrying a big mortgage. Higher rates push repayments up, while inflation pushes up insurance, maintenance, council rates and everyday living costs. If the rent does not keep pace, more and more after-tax salary goes into simply holding the property.
Then add falling values. Someone who bought near the peak may find refinancing harder, or their loan-to-value ratio going the wrong way.
And from July 2027, the negative gearing changes will make some personally held residential investments less tax-effective than they used to be.
The negative gearing changes matter
The 2026–27 Federal Budget split residential property into established properties and new builds. From 1 July 2027:
- Established residential investment properties bought after 7:30 pm AEST on 12 May 2026 will generally no longer allow rental losses to be deducted against wages and other non-residential income.
- Eligible new builds keep the existing negative gearing treatment.
- Established properties held before the Budget announcement are grandfathered.
- Unused losses on affected properties can be carried forward and used against residential rental income or residential property capital gains.
For investors who relied on negative gearing to cut their personal tax bill each year, that is a big shift. The property now has to stand on its own two feet, rather than lean on deductions against your salary.
We unpacked the full Budget changes in our My SMSF Budget Review 2026.
3. Why SMSF Property Tax Deserves Another Look
Here is the detail in the Budget that every SMSF trustee should know: super funds, including SMSFs, are excluded from the new negative gearing restriction.
Your fund’s property expenses and permitted borrowing costs continue to be assessed under the normal super tax rules.
To be clear, that does not mean an SMSF can offset property losses against your personal salary. It cannot and it never could. What it means is that the fund’s tax treatment has not been touched by the new restriction on personally held residential property. An SMSF with allowable rental losses can generally still use those deductions against other assessable income inside the fund, subject to the usual tax rules.
For an existing SMSF property portfolio, that distinction is likely to become more valuable over time.
Capital gains tax is another big difference
The Budget also changed capital gains tax for individuals, trusts and partnerships from 1 July 2027. The 50% discount is replaced with inflation-based cost base indexation and a minimum 30% tax rate on relevant gains. Gains accrued before commencement are protected by transitional rules and special choices apply to eligible new-build residential investments.
Complying SMSFs stay under their own CGT framework:
- In accumulation phase, capital gains on assets held at least 12 months generally have an effective tax rate of 10%.
- Income and gains on assets supporting eligible retirement-phase pensions may be tax-exempt.
- That retirement-phase exemption is subject to the pension standards and the transfer balance cap.
Over a long holding period, those differences can be significant. They are not unlimited, though. Division 296 adds tax on super earnings for members with total super balances above $3 million, with a further layer above $10 million from 2026–27. Our article on Div 293 and Div 296 in an SMSF explains how that works.
Even so, the combination of fund-level tax and potential retirement-phase concessions is a key reason to think carefully about which structure you hold property in.
4. The 15–25 Year Horizon: Time Is on Your Side
For most of our clients, the property in their SMSF is not something they plan to sell next year. The horizon is 15, 20, even 25 years.
Over that kind of timeframe, the questions that matter for SMSF property are not this weekend’s auction clearance rate or next month’s interest rate decision. They are: can the fund keep servicing its commitments, keep the property maintained and hold enough liquidity until retirement?
Australian property has been through downturns and recoveries before, but the timing and strength of any recovery vary a lot between markets and properties. A long horizon reduces the chance you will have to crystallise a loss in a temporary downturn. It does not guarantee growth and it will not rescue a loan that was never sustainable.
For an SMSF with ongoing contributions, steady rent and a diversified pool of other investments, a falling market can usually be ridden out without an early sale.
The goal is not to pick the bottom of the market. The goal is to stay strong enough that you are never a forced seller.
5. The Catch: New SMSF Residential Property Loans Are Restricted
There is one big legislative change you cannot ignore. Since 10 August 2026, SMSFs have generally been banned from setting up new limited recourse borrowing arrangements (LRBAs) to buy ordinary residential investment property.
However:
- Qualifying residential LRBAs set up under the old rules continue.
- Existing eligible residential LRBAs can generally be refinanced.
- SMSFs can still buy residential investment property outright, without borrowing.
- New borrowing is still available for eligible business real property, subject to SMSF and lender requirements.
So the advantages I have outlined apply most to existing SMSF residential property owners, cash-funded residential purchases and qualifying business real property. It would be wrong to suggest you can set up a new residential LRBA to take advantage of lower prices. You cannot.
For more on what the ban does and does not affect, read The SMSF Residential Borrowing Ban — Where to From Here?
6. Could Falling Prices Be a Long-Term SMSF Opportunity?
A falling market is not bad news for everyone. For an SMSF with enough cash and a long horizon, lower prices can improve the numbers on a purchase.
The real test is whether the price, expected net income, running costs and remaining liquidity all stack up against your investment strategy. A lower price may lift the gross yield if rents hold, but higher holding costs, vacancies or falling rents can eat that benefit.
- Buying with cash: no interest expense, which makes the property’s cash flow far more resilient.
- Buying business real property with a loan: the deal still has to survive conservative interest rate and rent assumptions.
Do not forget concentration risk. Tying up a large share of the fund in one illiquid asset needs to be justified, especially as retirement gets closer and pension payments start. If you are weighing up your options, see Can Your SMSF Still Buy Property in 2026–27?
7. What Should Existing SMSF Property Trustees Do Now?
Do not react to the headlines. Review your fund’s financial resilience instead. That means looking at:
- Actual cash flow: rent, contributions, investment earnings, loan repayments and fund expenses.
- Debt servicing: whether your SMSF property loan stays affordable if interest rates rise again or rent dips for a while.
- Liquidity: how much accessible cash is left after allowing for repairs, vacancies, tax, audit and other costs.
- Valuations: whether the reported property value is backed by current, objective evidence.
- Investment strategy: whether the fund is still diversified enough and suits your retirement needs.
- Retirement timing: whether contributions will keep coming and how future pension payments will be funded.
In our experience, these practical checks matter far more than any short-term market forecast.
My SMSF Rental Manager
If you self-manage your fund’s rental property, keeping costs under control and records in order matters even more when money is tight.
Our SMSF Rental Manager gives you tenancy checklists, expense tracking, rental summaries, property reviews and an optional Airtasker connection for finding tradies and service providers. You stay in charge of the tenancy and property decisions; it just makes the record-keeping and cost tracking a lot easier.
8. Is SMSF Property More Attractive After the 2026 Budget?
For some investors, yes, particularly where the SMSF already holds property, can buy with cash, or is buying eligible business real property.
The attractions include:
- 15% tax on net investment income in accumulation phase.
- Extra liquidity from contributions and other fund investments.
- The SMSF capital gains tax framework, which the Budget left in place.
- Exclusion from the new negative gearing restriction.
- Potential tax-free income in retirement phase.
But it is not the right answer for everyone. If you are on a lower personal tax rate, need access to your capital before retirement, have a modest super balance, or need a lot of liquidity, you may reach a different conclusion. SMSF property also comes with set-up and running costs, trustee responsibilities, investment restrictions and more complex financing.
Structure is only part of the decision. The property itself still has to be a good investment. For a deeper look at the structural case, see The SMSF Property Advantage.
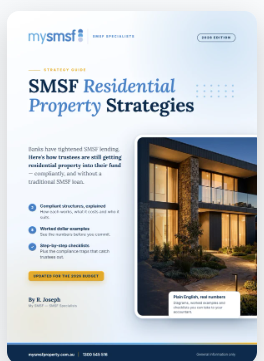
Exploring Residential Property Through Your SMSF?
The rules have changed, but the opportunities haven’t disappeared.
Discover practical, compliance-focused ways to acquire residential property through your SMSF without an LRBA.
Our new SMSF Residential Property Strategies eBook explains alternative structures, costs, worked examples and important compliance considerations.
Just $7.70 — an accessible guide for trustees planning their next property investment.
Buy & download your SMSF Residential Property Strategies eBook — $7.70
The Bottom Line: Structure, Cash Flow and Time
Inflation, high interest rates and falling values are testing every property investor in Australia, but they are not hitting everyone equally.
An SMSF property investor with three cash-flow sources, a manageable existing loan at today’s interest rates and a long runway to retirement has a lot of flexibility to get through tough conditions. A personally held investment property is more exposed to household spending pressure, borrowing costs and the new tax treatment of residential investments.
The 2026 Budget has made those differences more important to understand and with interest rates where they are, SMSF property trustees who plan ahead are in a stronger position.
For SMSF trustees, the question is not just whether property prices will recover. It is whether your fund is structured and funded to stay resilient until they do.
And if you are considering property inside super for the first time, the question is whether the tax benefits, contribution capacity, liquidity and available buying options justify the extra responsibilities and restrictions.
Review Your SMSF Property Strategy With My SMSF
At My SMSF Property, we help trustees with SMSF establishment, property administration, accounting, tax compliance and audit coordination.
Explore our SMSF Property Investment Guide or contact the My SMSF team to talk through what holding property in your fund involves. You can also call us on 1300 545 516.
Frequently Asked Questions
Is rental income taxed at 15% inside an SMSF?
Net assessable rental income is generally taxed at 15% in the accumulation phase of a complying SMSF, after allowable deductions. Income from assets supporting qualifying retirement-phase pensions may be exempt. Special rules apply to non-arm’s-length income and to members with larger super balances.
Can an SMSF use super contributions to repay a property loan?
Yes. Eligible contributions received by the fund generally become part of its available cash for meeting permitted liabilities, including repayments on a compliant existing LRBA. Contributions are still subject to the caps, eligibility rules and contributions tax.
Can an SMSF still buy residential property after the 2026 borrowing changes?
Yes. An SMSF can generally buy eligible residential investment property without borrowing, subject to its trust deed, investment strategy and super law. Since 10 August 2026, new LRBAs to buy ordinary residential property have generally been prohibited, while eligible existing arrangements can continue and be refinanced.
Does the negative gearing change apply to SMSFs?
No. Super funds, including SMSFs, are excluded from the new restriction that starts on 1 July 2027. An SMSF’s allowable property losses continue to be dealt with under the normal super fund tax rules. They still cannot be used against a member’s personal income.
Sources and Further Reading
- Reserve Bank of Australia — November 2026 Statement on Monetary Policy
- Australian Treasury — 2026–27 Federal Budget tax changes
- ATO — Self-managed super funds
- My SMSF — 2026 Federal Budget Review
- My SMSF — Proposed Australian Tax Changes 2026: Impact on SMSFs and Property Investors
- My SMSF — Property Investment Guide
Disclaimer: This article provides general information only and is not personal financial, investment, legal or tax advice. My SMSF Property provides SMSF administration, accounting and related support services. Tax outcomes depend on individual circumstances and trustees should obtain appropriate licensed financial advice and professional tax advice before making investment or restructuring decisions. Information is current as at November 2026.